Salary, rent, school fees, utility bills: almost everything in UAE life runs through a bank account, which is why people tend to sort one out in their first weeks. If Emirates NBD is on your shortlist, a little preparation can save you several return trips.
Below is a practical guide for personal accounts. The bank decides every application and updates its conditions from time to time, so treat this as a map and confirm details with the bank before you apply.
01Current or savings: choose by how you use money
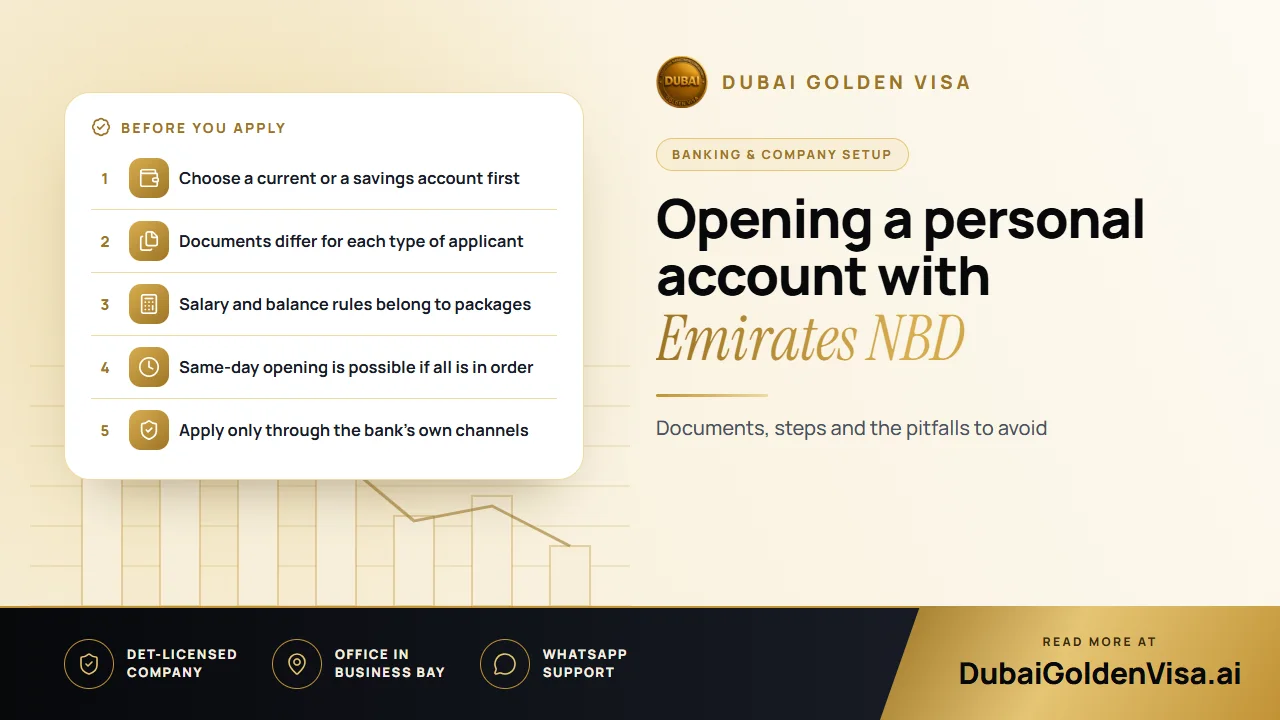
Begin with what you want the account to do. If your pay will land there and you will use it for cards, transfers and bills, a current account is usually the natural fit. Look at whether a debit card or cheque book comes with it, whether a package expects a salary transfer, and what happens if your balance dips below a required level.
A savings account suits money you want to keep apart. Interest, balance conditions and withdrawal rules vary, so do not assume every savings product pays the same or lets you withdraw without limits. For whichever product you favour, read the Key Facts Statement and the Schedule of Charges. An account loaded with extras is no bargain if you will not use them.
02Who can apply
The bank deals with both UAE residents and non-residents, though the products and paperwork differ. Residents generally show identity documents and may be asked about their job or income. Non-residents should expect extra questions, such as an overseas address and proof of an existing banking relationship. Some products and digital routes also carry an age condition, so check the terms of the one you pick.
Remember that applying is not the same as being approved. The bank carries out its own checks and can ask for more information before it decides.
03Documents to prepare
The list below shows typical examples. Your own checklist may be shorter or longer, depending on your situation and the account.
- UAE resident: passport, Emirates ID and residence details
- Salaried applicant: a salary transfer letter, employment contract, recent payslip or proof of a salary payment
- Non-resident: passport and visa page, proof of address abroad, and a bank reference or recent statement from your existing bank
- Self-employed: personal identification plus evidence of where your income comes from
Check that nothing has expired and that scans are sharp. Names and dates should be identical across every document. If you have recently moved or changed jobs, ask what the bank will accept as current proof. A personal account is also not meant for company transactions; if you will bank for a business, ask about a business product instead.
04Applying online
Digital opening is available for eligible products and customers. Begin on the bank's own website or app, never from a link sent by a stranger or a message asking you to upload your ID to an unfamiliar page.
- 1
Compare and choose
Read the conditions of the current and savings options before selecting one.
- 2
Pick the new-customer route
Use it if you do not already hold an account with the bank.
- 3
Enter your details
Copy your name, contact information and address exactly as they appear on your documents.
- 4
Verify your identity
Follow the prompts for Emirates ID, passport or any other check requested.
- 5
Upload clear supporting files
Documents must be readable and belong to you.
- 6
Review and submit
Fix mistakes before sending and save the reference number.
- 7
Watch for follow-up
The bank may ask for another document or an explanation.
05Applying in a branch
A branch is helpful if you are unsure which product fits or your circumstances need explaining. Bring your originals and whatever supports your situation, such as salary evidence or, for a non-resident, the overseas address and banking papers. Phone ahead to ask whether you need an appointment.
06Salary rules, balances and fees
There is no universal minimum salary. The bank's Key Facts Statement lists a salary requirement of AED 5,000 for the salary version of certain named packages, but that applies to those packages only. Other products may use a minimum balance instead, with a fee if you fall short.
The bank states that most accounts carry no opening fee, though individual products can have their own joining or monthly charges. Look at the current schedule for charges linked to balances, cards, transfers and transactions beyond a package allowance, and ask about anything unclear before you sign.
07How long it takes, and why it stalls
The bank says an account may open on the same day when every document is supplied. Treat that as a best case. Delays usually come from a missing page, an out-of-date salary letter, a name that differs from the passport, or a request to explain the source or purpose of funds. Such a request is routine due diligence, not a rejection.
Tip
Be honest with the paperwork
Never alter a statement, borrow someone else's proof of address or state income you cannot support. If an application is declined, ask whether another account might suit you better.
Once the bank confirms the account is active, set up digital access and your card, tell your employer where to send your salary, and keep your phone number and email up to date. If you would like help working out which documents apply to you, message us on WhatsApp for a free check before you apply.
Questions about this topic
Yes, for eligible products and customers. Use the bank's official website or app and follow its verification steps.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.