

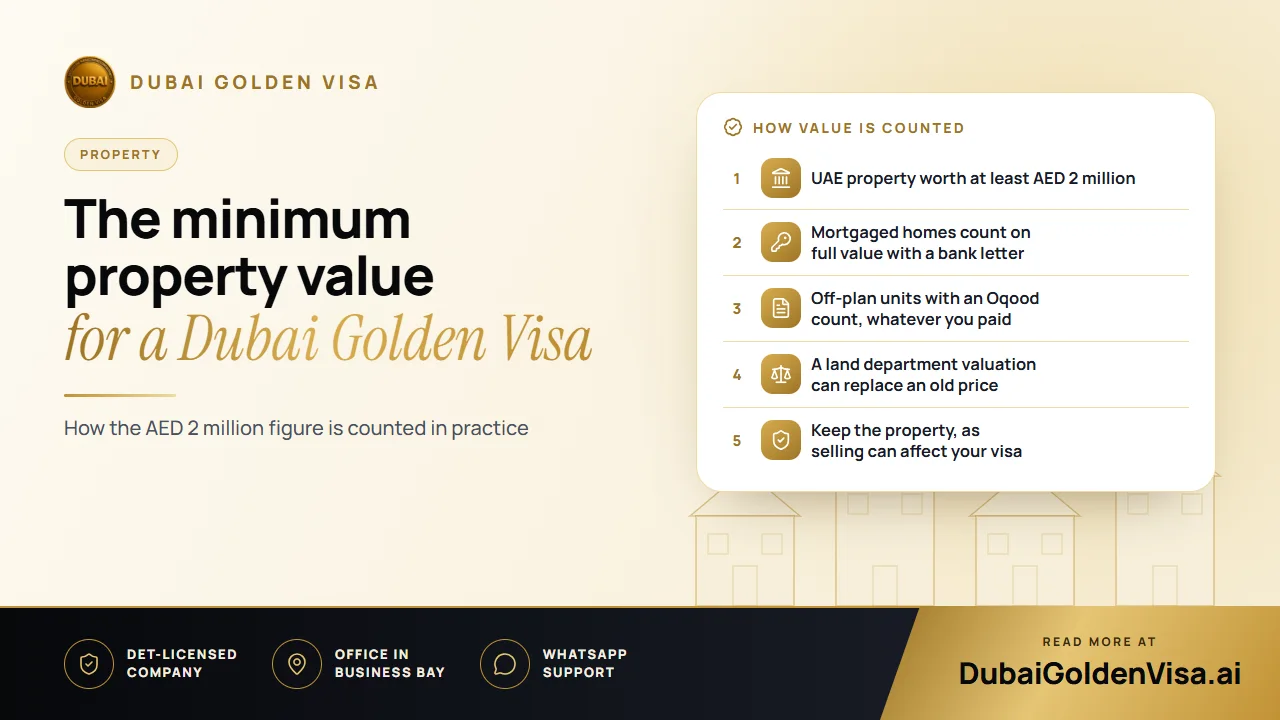
If you are thinking of buying in Dubai partly for the residence it can bring, the first thing to settle is the budget. The figure is AED 2 million, roughly half a million US dollars, and it is the entry point to a ten-year Golden Visa through property.
The number itself is simple. What trips people up is how it is measured, so let's go through the situations buyers ask about most.
01One property or several
You do not need a single AED 2 million home. Values from several properties can be added together, so one apartment in Downtown and a smaller unit elsewhere in the city can add up to the required amount, provided they are all registered in your name.
If you share a property with someone else, the usual approach is to look at your own share rather than the whole price, so check how the deed is divided before you assume you qualify.
02Mortgaged homes
Buying with a loan does not disqualify you. A mortgaged home can count on its full value, which means you do not need AED 2 million in cash. What you do need is a no-objection letter from the bank that holds the mortgage, confirming it is content for the property to be used for the visa.
This changed over the last couple of years. It was once common to hear that a large minimum down payment was required, but buyers are now generally assessed on the property's value rather than on how much of it they have paid off.
03Off-plan properties
A home that is still being built can count too, as long as it has been registered with the land department through an Oqood and was bought from a developer the authorities approve. The amount you have paid so far does not change that, though it is sensible to keep your payment schedule and developer letters ready.
Freehold areas are where foreigners can buy, so make sure the community you are looking at is one of them. Popular ones include Downtown, Dubai Marina, Palm Jumeirah, Business Bay and Jumeirah Lake Towers.
Tip
Old deed, lower price?
If you bought years ago and the deed shows less than AED 2 million, a current valuation from the Dubai Land Department can be used instead of the original price. Prices have risen in many areas, so you may qualify without buying anything new.
04Documents and costs
- Title deed, or Oqood for an off-plan unit.
- A valuation certificate, where the deed price is low or one is requested.
- Bank no-objection letter if there is a mortgage.
- Passport, Emirates ID if you already have one, and recent photographs.
- Health insurance and, later, a medical test.
As a guide, the government cost for the main applicant on the property route is about AED 9,459, covering the land department charge, immigration, the Emirates ID and the medical test. Each family member adds roughly AED 2,710 plus AED 1,180 for the Emirates ID, and AED 285 for an adult's medical. Property files usually take five to seven working days once everything is complete.
05Why the threshold is set where it is
AED 2 million is a commitment large enough to show a genuine stake in the country, but within reach of many middle-income investors who buy a good apartment or two. It sits alongside other routes, such as a company stake, a salary of AED 30,000 or an approved fund, so property is one of several doors rather than the only one.
06Renting out, selling and family
You do not have to live in the property yourself, and many owners rent it out. Selling is different: if a sale takes your holdings below the threshold, your residence can be affected, so plan the visa and the property together. Once your visa is issued, your spouse, your children and your parents can be added, and household staff are covered too.
Want to know whether the property you own or plan to buy is enough? Message us on WhatsApp for a free check and we will look at your deed, valuation and mortgage position with you.
Questions about this topic
Yes, as long as both are registered in your name and their combined value reaches the threshold.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.



