

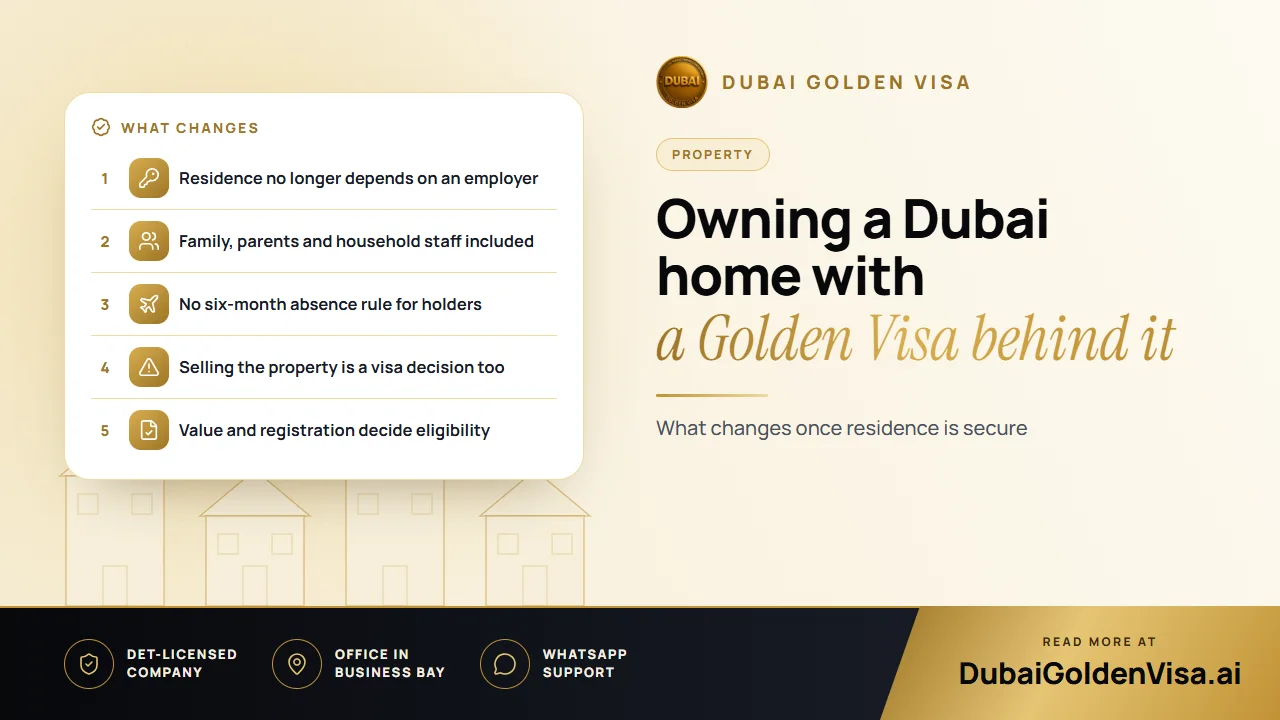
For years, buying in Dubai meant owning bricks while your right to be here belonged to somebody else. A job could end, a company could close, and a perfectly good property could sit in a country where you could no longer live.
A Golden Visa changes the relationship between the owner and the home. This guide looks at what shifts, what stays the same and what to check first.
01The basics in one place
The property Golden Visa gives ten years of renewable residence to an owner holding AED 2 million or more of qualifying property. That can be one home or several, registered in your own name. A mortgaged home can count on its full value with the bank's no-objection letter.
It is not enough to own something. The authorities check the value that the land department recognises and the way the property is registered, so documents matter as much as the purchase.
02What actually changes for the owner
- Residence security: no employer or sponsor, so a career change does not touch your status
- Family stability: spouse, children and in many cases parents can be included
- Travel freedom: no six-month absence rule that cancels a standard residence visa
- Financial standing: banks see a long-term resident, which can help with accounts and mortgages
- Planning: ten years lets you think about schools, retirement and succession without a short-term visa clock
Family cover is often the deciding factor. Sons can stay with no age cap and unmarried daughters at any age, which standard visas do not allow. Household staff can be added without the usual caps.
Tip
Banks look more kindly, but they decide
Long residence usually makes a bank more comfortable, but each bank sets its own rules. A Golden Visa does not guarantee an account, a mortgage or a refinance.
03What does not change
Not every purchase is automatically eligible. An off-plan unit needs an approved developer and an Oqood. Land is treated more tightly than a finished apartment or villa, and its eligibility depends on how it is zoned and registered. A purchase made through a company is different from one made in your own name, so structure it before you buy.
An informal valuation or a developer's marketing price carries no weight. If your deed shows an old, lower value, a current valuation from a firm the land department recognises can replace it. A value that falls under AED 2 million by renewal time can cause trouble, so keep an eye on it.
04Selling, renting and living in it
Renting your property out does not harm your visa, and neither does leaving it empty. You also do not have to live in it. What does matter is selling: if the property is the one behind your visa, selling it can end your residence unless you have a replacement in place. Plan the order of buying and selling before any contract is signed.
Joint owners need extra thought. Generally each owner needs a registered share worth AED 2 million or more to qualify in their own right, so a jointly owned home does not automatically give every co-owner a visa.
05Designing the purchase around the visa
- 1
Decide who will hold the visa
Choose which person's name goes on the title, and how any co-owner or spouse will be covered.
- 2
Check the unit's eligibility
Confirm it is registered and, if off-plan, from an approved developer.
- 3
Confirm the value
Make sure the figure the authorities recognise clears AED 2 million.
- 4
Prepare the bank letter
If you are financing it, ask the lender for the no-objection letter early.
- 5
Apply once registered
File as soon as the deed or Oqood exists, then complete the medical test and Emirates ID.
Thinking of buying with residence in mind? Message us on WhatsApp for a free check of the property and the way you plan to hold it, before you pay a deposit.
Questions about this topic
Yes. Renting does not affect your eligibility, and nor does living in the property or leaving it empty.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.



