

For most buyers, a mortgage is simply how a home gets bought. Few people pay cash for an AED 2 million apartment, so it would be odd if borrowing ruled out the Golden Visa. It does not. A mortgaged property can support a ten-year visa, provided a few conditions are met.
This guide explains those conditions in order, and clears up the old idea that you must first pay off half the price. If you have been told that, read on.
01The value rule, and the old payment rule
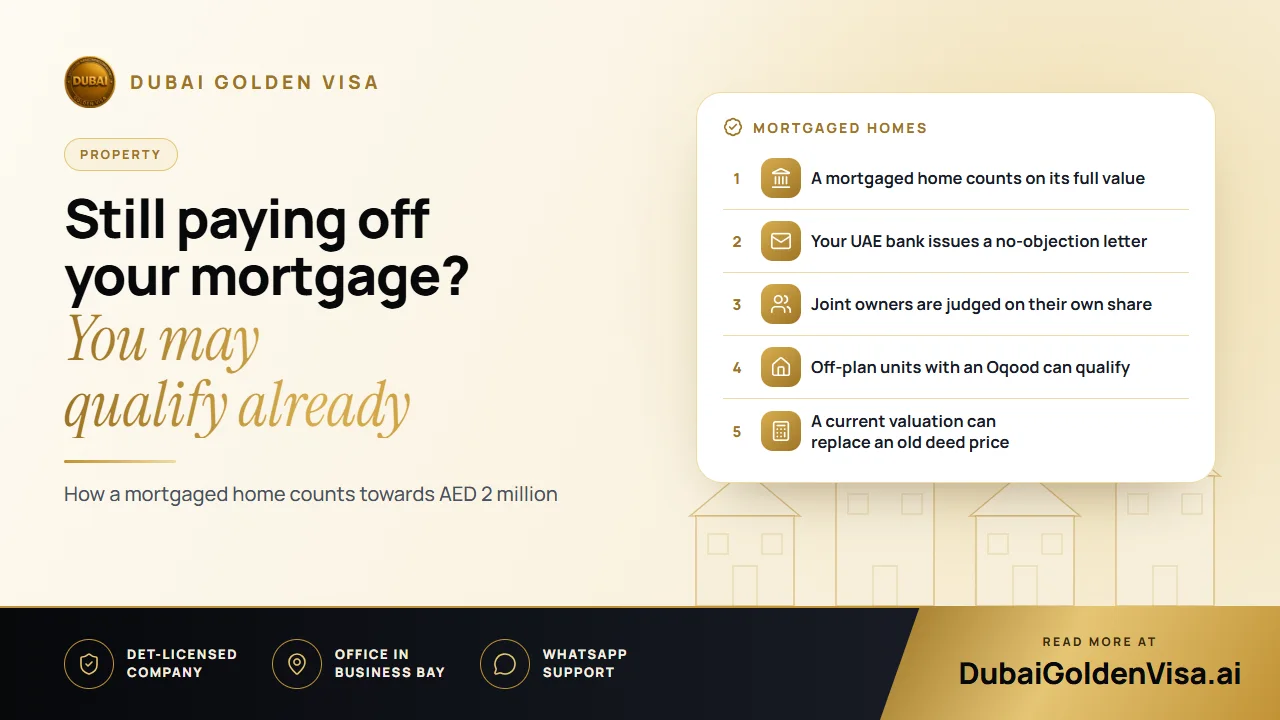
For years, many applicants were advised that they needed to have paid roughly half the price before applying. That view has been dropped. What counts today is the value of the property, not the amount you have already paid. A home worth AED 2 million or more qualifies on that value whether it is fully paid, mortgaged or bought through instalments.
The reference value normally comes from your title deed or, if the deed is old and the price low, from a current Dubai Land Department valuation. If the market has risen since you bought, the valuation may bring you over the line.
02What the bank has to confirm
Your lender needs to issue a no-objection letter. It states that the bank has no objection to a residence permit being issued on the strength of the property, and it shows how much has been paid and how much is still owed. The lender must be a UAE bank.
Ask for this letter early. Some banks take several working days, and a few have their own internal steps. A short call to your relationship manager before you apply can save a week.
Tip
Expect a lien
When a property supports a Golden Visa, a restriction is recorded against it so that ownership continues while the visa depends on it. That sits alongside your bank's mortgage. If you plan to sell or refinance later, talk to us first so the sequence works.
03Joint ownership and several properties
You do not need one single property worth AED 2 million. Several deeds in your name can be added together. Where you co-own, though, the test is applied to your share. If you and a business partner each own half of a AED 3 million apartment, your share is AED 1.5 million and does not meet the line alone.
Spouses are often treated more generously, so check how the deed is split and whether your marriage certificate is attested for use in the UAE. If you plan to combine properties, make sure each one is registered in your own name and you can get the statements or valuations for them.
04Ready homes and off-plan units
- Ready property: the title deed and the land department's value confirmation support the file.
- Off-plan property: your Oqood registration and the purchase price are used, and the developer must be approved. Payment made so far does not change eligibility.
- Mortgaged off-plan: expect the bank letter, and a developer letter where one is needed.
05Documents and process
- 1
Check your deed and share
Confirm the registered value, ownership split and whether you need a fresh valuation.
- 2
Get the bank letter
Ask your lender for the no-objection letter with the paid amount and balance.
- 3
File the application
Your file is submitted while you are in the UAE, or an entry permit brings you in if you are abroad.
- 4
Medical and Emirates ID
Complete the medical test and biometrics once your application is approved.
Property files with complete documents usually take around five to seven working days. The government cost for the main applicant is roughly AED 9,459, and each family member adds about AED 2,710 plus AED 1,180 for the Emirates ID and AED 285 for the medical test if they are adults.
06Common mistakes to avoid
The most frequent error is assuming the paid-up amount decides eligibility. The second is overlooking a joint deed and counting the whole price. A third is leaving the bank letter until the end, which holds the whole file up. We check all three before filing.
If you have a mortgage and want to know whether you can apply, message us on WhatsApp with a photo of your deed. We will do a free eligibility check and tell you which documents to request first.
Questions about this topic
The lender must be a UAE bank. Loans from overseas lenders are generally not accepted for this purpose.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.



