

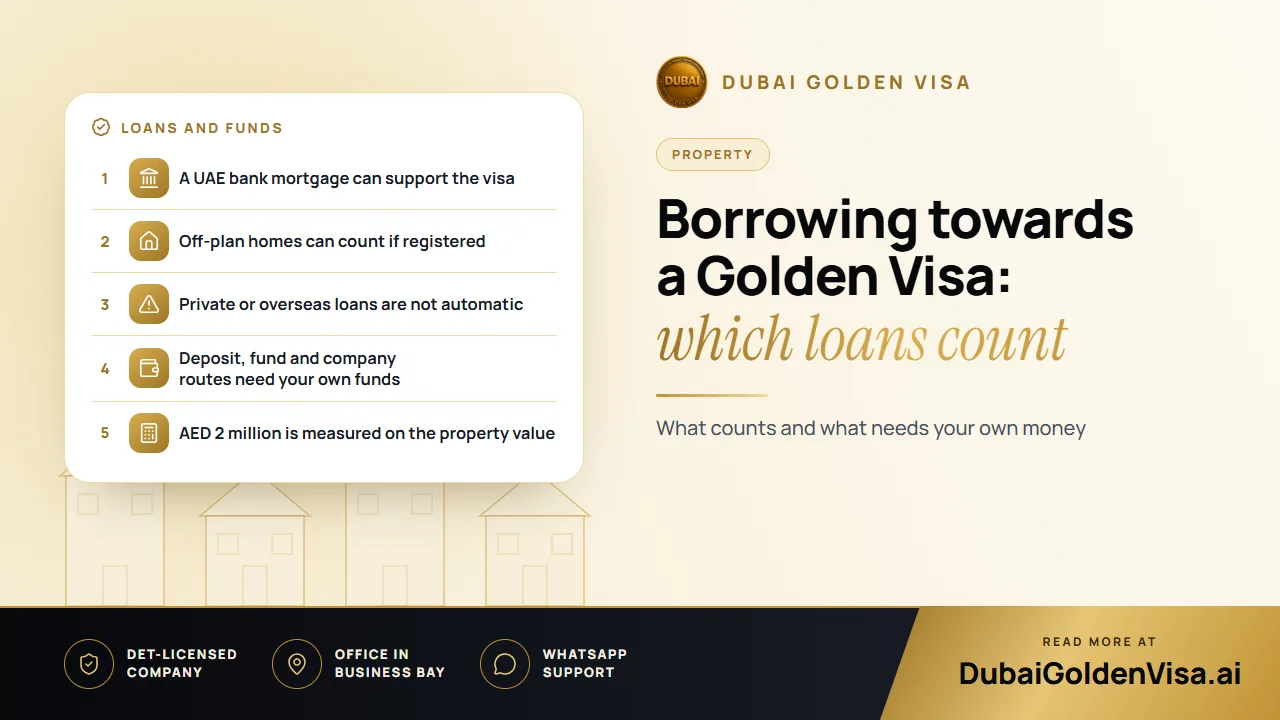
Most people who like the idea of ten-year UAE residency do not have AED 2 million sitting in a savings account. So the question comes up all the time: can borrowed money count? The answer is yes in some situations and no in others, and the dividing line is what you are buying.
Property is treated differently from a deposit or a company investment. Understanding why will help you decide how to fund your purchase before you sign anything.
01Why property is the exception
When you buy a home, you own a physical asset registered in your name with the Dubai Land Department. The bank may hold a charge over it, but the title deed is yours. The asset itself backs your residence.
Deposits, funds and company shares work the other way round: there, the cash is the investment. Borrow it and nothing of yours stands behind the visa. For those routes, the funds are expected to be yours, and the source may need to be documented.
02A mortgage from a UAE bank
This is the most common and safest way to use borrowed money. In the past, mortgage buyers faced a requirement to have paid a large share of the price before applying, which ruled out most people with a standard down payment. That has changed: a mortgaged home can now count on its full value, provided the bank issues a no-objection letter.
To put numbers on it, imagine a flat bought for AED 2.4 million with a 20 per cent deposit and a bank loan for the rest. The property's full value is above the threshold, so the home can qualify even though the bank funded most of it. Ownership, value and bank papers are still checked, so approval is never automatic.
03Personal, family and overseas loans
This is where buyers should be careful. The accepted route is finance through a UAE bank. Money borrowed from a relative, a friend or a private lender is not automatically treated like a mortgage.
If you borrowed AED 2 million from a friend and bought a home in your own name, the property might exceed the threshold, but the way you funded it could still be questioned. Overseas bank loans face a similar problem. Get the position confirmed in writing before you commit.
04Off-plan on a payment plan
A developer's payment plan is another form of staged funding. An off-plan unit can count from the day your Oqood is registered, whatever you have paid so far, so you do not need to wait for handover. Two things must be in place:
- The developer is approved and the unit is registered with the land department.
- The contract value and your ownership can be documented.
An unregistered off-plan unit is one of the most typical reasons for refusal, so check registration before paying large instalments.
05If your property is already mortgaged
You can still apply. The bank letter should state the purchase value, the amount you have paid, the outstanding balance and that the bank has no objection to a residence application based on the property. Banks can take a number of working days to issue it, so request it early.
06Rules to keep in mind
- The AED 2 million is based on the property's recognised value, and a current valuation can replace an older, lower deed price.
- The transfer fee is 4 per cent of the price and is not counted towards the AED 2 million.
- The property must be in your name in an area where foreigners can own.
- Two or more properties can be combined if each is properly documented.
- Deposit, fund and company-capital routes need your own funds.
- The visa runs for ten years and is renewable while you meet the conditions.
Tip
Do not buy at exactly AED 2 million
If the recognised value comes in even slightly below the line, the application can fail, however much you paid. Choose a property comfortably above the threshold or confirm its value first.
07A sensible order of steps
- 1
Get mortgage pre-approval
Speak to a UAE-licensed bank so you know your budget.
- 2
Choose a qualifying property
Pick a home where owners can buy, with a value that leaves some margin.
- 3
Register the purchase
Make sure the title deed or Oqood is registered in your name.
- 4
Ask for the bank letter
Request the no-objection and balance letter early.
- 5
Confirm the value
Obtain a valuation if the deed shows a lower figure.
- 6
File the application
Submit it with passport, photos, health insurance and property papers.
08Mistakes that cost time
- Applying before the bank letter is ready.
- Relying on private or foreign loans without checking.
- Using an old guide that quotes earlier payment rules.
- Taking on a loan that stretches your budget.
The last of these deserves a second look. A mortgage is secured on your home, so if repayments stop the bank can enforce against the property, and the basis of your visa goes with it.
Planning to finance a purchase? Message us on WhatsApp for a free check of your property, loan structure and paperwork before you commit.
Questions about this topic
Yes, if the property is worth AED 2 million or more and your UAE bank provides a no-objection letter.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.



