

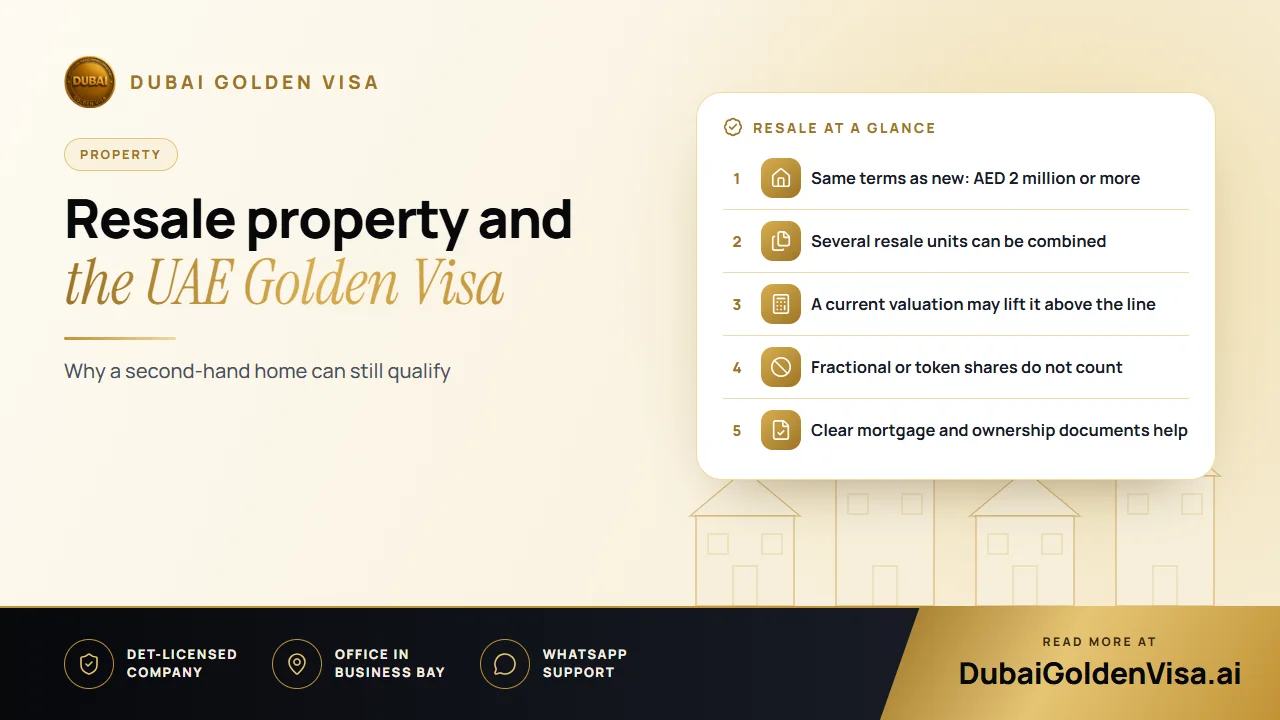
Developers promote the Golden Visa heavily alongside new launches, so it is easy to come away thinking that only off-plan homes qualify, or that a resale unit is somehow second best. Neither is true.
What the authorities care about is what you own, what it is worth and whether the paperwork is clean. How old the building is, and whether you bought from a developer or a previous owner, does not come into it.
01What a resale home needs
- A value of AED 2 million or more, recorded with the land department.
- A title deed issued in your name.
- No legal dispute on the property.
- Any mortgage documented clearly, with the bank's no-objection letter.
A flat you bought in 2018 and a villa you buy next month are treated alike if they meet these tests. A resale unit also has practical advantages: the deed already exists, the building is finished, rental history may be on record and there is no construction delay to worry about.
02When the price you paid is lower than today's value
This is a common route for people who are already owners. You may have paid AED 1.6 million some years ago in an area that has since appreciated. If a valuation from a firm approved by the land department now puts the unit at AED 2 million or above, that figure may be used to support your application, subject to the file being reviewed.
The same logic helps owners of two smaller flats. Adding their values together can clear the bar, provided the deeds are all in the same name.
Tip
Tokenised shares are a different thing
Dubai has been developing digital, blockchain-based fractional ownership of property. A fractional or token holding is not the same as a registered title deed, and it does not support a Golden Visa. Only direct ownership recorded in your name counts.
03Mortgaged resale homes
A mortgage on a resale unit is not an obstacle. The home counts on its full value once the bank issues a no-objection letter. We usually also ask for a mortgage statement showing the outstanding balance and what has been repaid, because a clear picture speeds up review.
Most delays we see on resale files do not come from the property being ineligible. They come from a missing bank letter, an unclear mortgage statement or a deed that does not match the application.
04What can trip up a resale file
- A private valuation that is well above the figure the land department recognises.
- Property owned through a company, which needs structuring before it can support a personal visa.
- Mismatched names or details between the deed and your passport.
- A mortgage that has not been recorded properly with the land department.
05A sensible order of work
- 1
Pull your title deed
Check your name, your share and the registered value.
- 2
Compare with today's value
If the deed value is under AED 2 million, ask whether a valuation could help.
- 3
Collect finance papers
For a mortgage, request the bank letter and a recent statement.
- 4
Submit with a complete file
A complete file avoids the back-and-forth that slows approvals.
Once the visa is issued, ordinary swings in the market are not treated as a reason to cancel it, but selling the home is a different matter, so plan any sale with care.
Own a resale home and wondering if it is enough? Send us a photo of your deed on WhatsApp for a free check.
Questions about this topic
Neither is safer in the rules. What counts is the registered value, your ownership and the documents.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.



