Plenty of owners bought a Dubai apartment for AED 1.6 or 1.8 million, assumed the Golden Visa was out of reach, and moved on. Since then, many areas of the city have grown in value. If that describes you, you may already be closer to the threshold than you think.
The property route asks for UAE property worth AED 2 million or more. This article explains how rising values fit into that test, what proof is needed and where appreciation stops helping.
01Value now, not price then
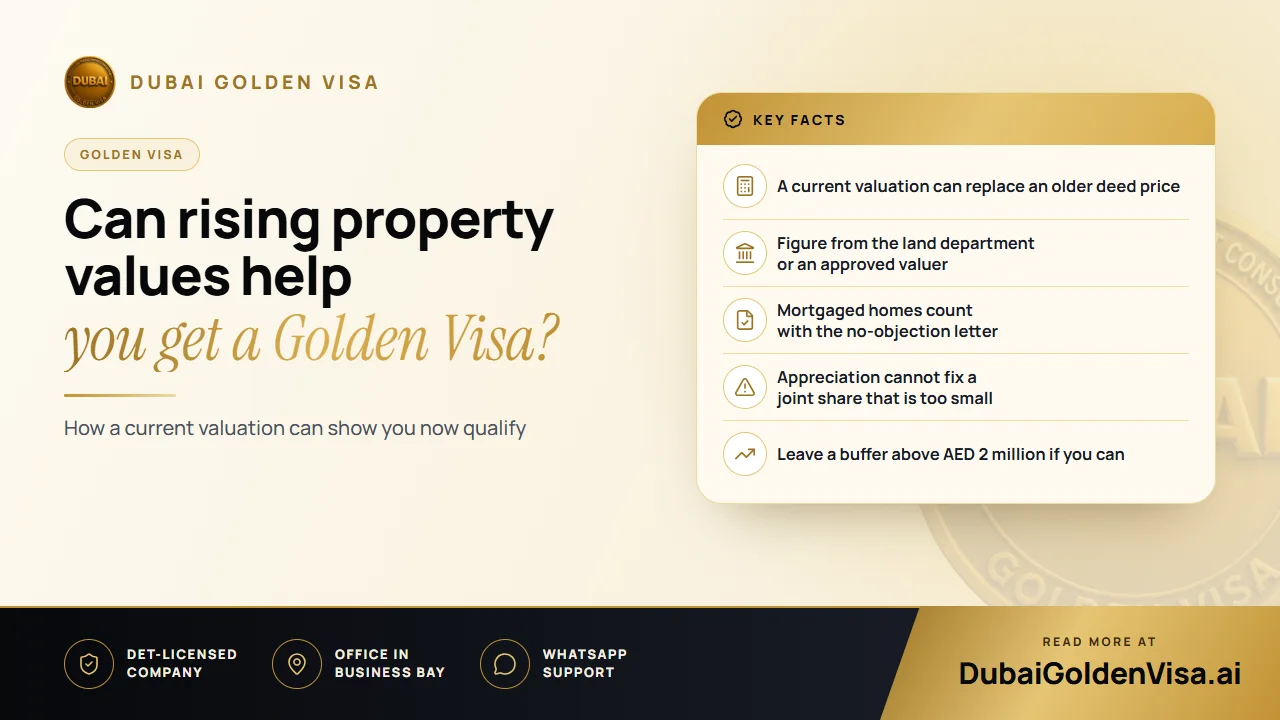
The threshold is about value, and a current valuation can replace an older deed price. If you bought for AED 1.7 million and the home is now valued at AED 2.1 million, that valuation can support an application. The property may be a single unit or several added together, as long as they are in your name.
This also applies to mortgaged homes. A home valued at AED 2.5 million still counts on its full value, even with a large balance outstanding, provided your bank issues a no-objection letter. What you have paid off does not reduce the figure that counts.
Tip
An estimate is not enough
Online listings, agent opinions and your own sense of the market will not be accepted. The value has to be certified by the land department or a valuer it approves.
02The valuation certificate
The valuation is the document that turns market movement into eligibility. It comes from a firm licensed by the Dubai Land Department and carries a verifiable reference. Without it, appreciation has no legal weight in your file.
Valuations reflect a moment in time, so we usually arrange one close to the filing date. If it is too old, you may be asked for a fresh one.
03How different properties are treated
- Ready homes: a certified valuation of AED 2 million or more is the key document alongside your deed.
- Mortgaged homes: the full value counts once the bank provides its no-objection letter.
- Off-plan units: with an Oqood from an approved developer, the unit can count whatever you have paid, though the value recognised is what the land department confirms.
- Several properties: values add together, so two units that each fall short can still clear the line in total.
04When growth is not enough
Rising value cannot rescue a file with other weaknesses. If you co-own, it is your own share that has to reach AED 2 million, and a larger overall price does not change that. The property also needs to be registered in your name, and a mortgaged home needs the bank's letter.
Values can also move the other way. A buyer who paid AED 2.3 million at a market peak could see a new valuation land under the line. If you are just above AED 2 million, a modest fall could put you under it, so a buffer is sensible if you are choosing which property to rely on.
05Checking whether you qualify today
- 1
Gather your deed
Confirm whose name it is in, your share and the registered value.
- 2
Get a current valuation
Ask a licensed valuer for a certificate, or let us arrange one.
- 3
Compare with the threshold
Add up all eligible properties in your name, and note any mortgage.
- 4
Prepare the file
Collect your passport, insurance, photo and, if needed, the bank's letter.
- 5
Apply promptly
Straightforward property files usually take 5 to 7 working days once documents are complete.
Once the visa is issued, keep your property documents safe. You may be asked about your ownership again at renewal, and if you plan to sell, talk to us first so we can plan your next status.
Wondering whether your home has grown into Golden Visa range? Send us a photo of your title deed on WhatsApp for a free check. We will tell you whether a valuation is likely to help and what to do next.
Questions about this topic
No. The value must be certified by the land department or an approved valuer, so a broker quote will not be accepted.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.