Homeowners refinance for many good reasons: a lower rate, a smaller monthly payment, or cash to put into something else. If your Golden Visa rests on a Dubai property, though, it is natural to wonder whether changing the loan could shake your residence.
In most cases it should not. A property-based Golden Visa is tied to what you own, not to who lends you the money. Still, a few situations call for care, and it helps to know them before you sign a new mortgage.
01What refinancing changes and what it does not
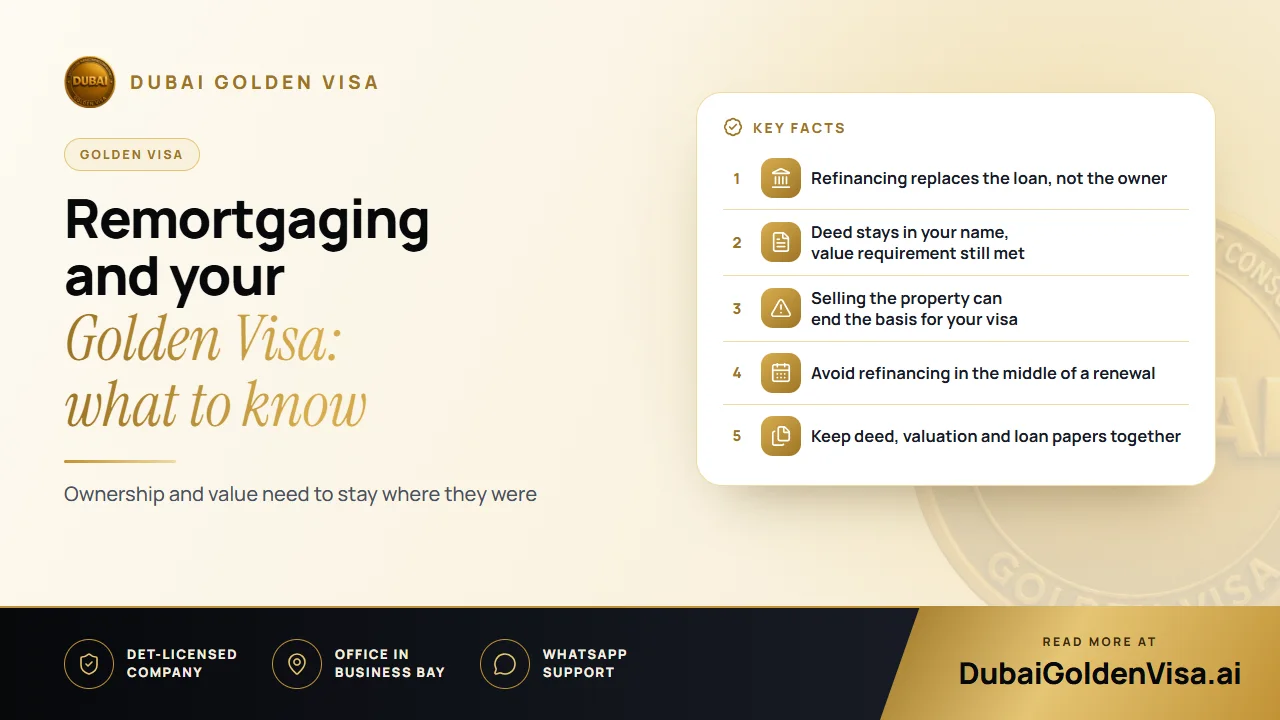
When you refinance, a new loan pays off the old one. The home stays registered in your name, the deed is the same, and you have not sold or transferred anything. A bank simply holds a charge over the property as security, as it did before.
The Golden Visa property route asks for UAE property worth AED 2 million or more in your name. A mortgaged home can count on its full value, backed by the lender's no-objection letter. So switching lenders or improving terms leaves the part the visa relies on untouched.
02Situations that deserve a second look
- Moving ownership shares: if the refinance involves adding or removing a name on the deed, your qualifying share could change.
- Releasing a lot of equity: the property should still meet the visa's value and ownership conditions afterwards.
- Using the cash to buy another property that you plan to count towards your total: make sure the combined value still works.
- Selling the refinanced property: if your visa rests on it, you may need another qualifying asset.
Tip
A simple rule of thumb
If the deed, the owner and the property's value are unchanged, a new mortgage on its own is not a visa event. If any one of those three moves, speak to us first.
03Timing around renewal
When your Golden Visa comes up for renewal, your status can be reviewed again. If a refinance is half-complete, a deed is being updated or the bank's paperwork is out of date, proving your position can take longer than it needs to.
The easiest fix is to refinance well before the renewal window or wait until the renewal is done. It costs nothing to plan this and removes a source of delay.
04Common refinancing choices and what they mean
- 1
Lower interest rate
You switch to cheaper finance with ownership and value unchanged. The visa is unaffected.
- 2
Equity release
You borrow against a property that has risen in value. Fine, so long as the property still meets the visa's conditions.
- 3
Changing banks
This is a decision between you and the lenders. Your residence does not depend on which bank you use.
- 4
Refinance then sell
Selling the qualifying property changes the picture completely. You may need to replace it to keep your visa.
05Keeping your visa safe while you refinance
- Check that the property still meets the AED 2 million requirement before, during and after the refinance.
- Keep the title deed in your own name and avoid any arrangement that changes who owns the property.
- Do not refinance in the middle of a renewal.
- Store your deed, any valuation and the mortgage agreement in one folder.
- Ask about banking and visa rules together, because the bank may not know the visa side.
Some banks offer attractive terms to Golden Visa holders, but compare the details yourself, and remember that every lender has its own conditions.
Planning a refinance, or about to renew your Golden Visa? Message us on WhatsApp and we will do a free check so nothing about your property catches you out.
Questions about this topic
No, not on its own. The visa follows ownership and value, and a refinance leaves both as they were.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.