Anyone who has bought property for a Golden Visa has probably wondered at some point: what if prices slip and my home is worth less than AED 2 million? It is a fair worry, particularly after a strong run in the market.
The reassuring part is that the rules were not built around daily prices. The less comfortable part is that other events can matter much more than a dip, so it pays to know which is which.
01How the threshold works in the first place
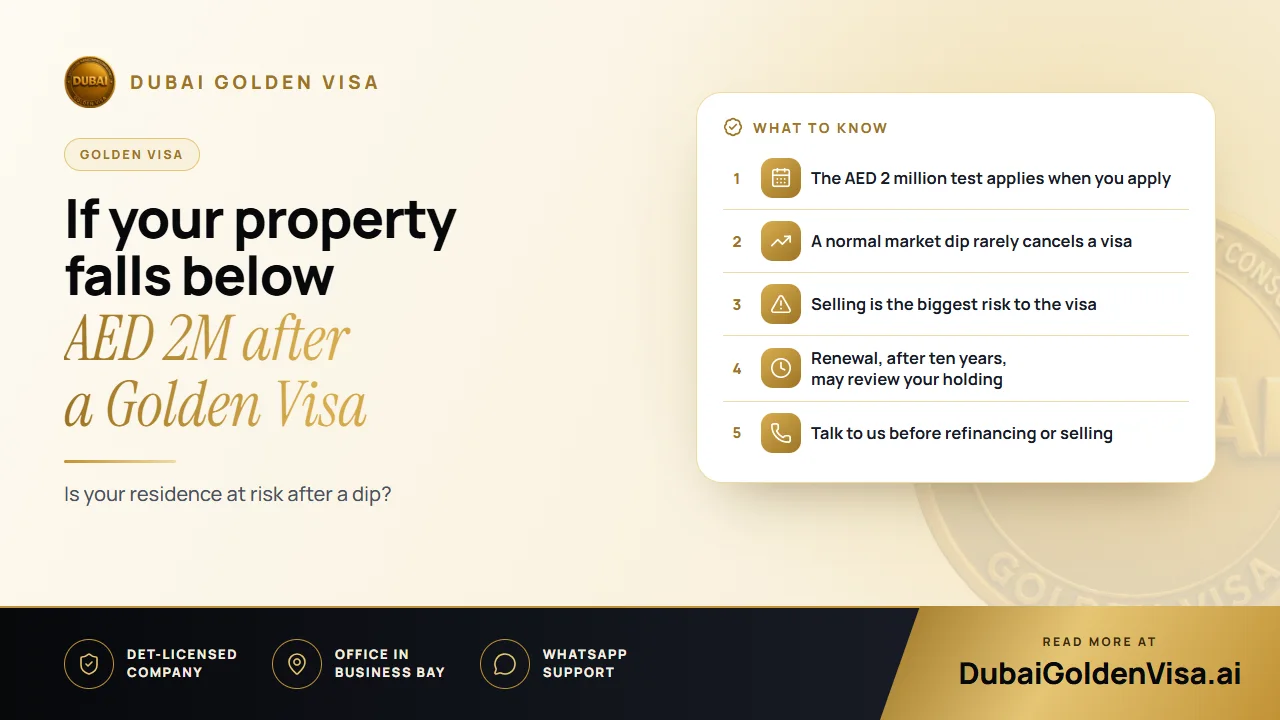
A property investor qualifies by owning UAE property worth AED 2 million or more, in a single deed or several, registered in their name. That value is tested when the application is made and approved. It is a snapshot at the point of qualifying, not an ongoing price feed.
02A market dip on its own
As far as we are aware, there is no yearly revaluation of Golden Visa properties and no trigger that cancels a visa because an area's prices have softened. Property markets move in cycles, and after a period of fast growth, some areas settling or correcting is normal. The visa rests on owning a qualifying property, not on beating the market.
That is our reading of current practice, though, and we always suggest you do not treat it as a promise for every circumstance. If your value has moved a long way, ask us about your specific file.
Tip
The honest caveat
Practice can change and individual files differ. If your property has fallen well below AED 2 million, do not wait for a problem to appear. Message us and we will look at the position with you.
03When value can matter again
- At renewal after ten years, when ownership and value may be reviewed again. If the recognised value is then well below AED 2 million, you might need to add a property, reduce a mortgage or restructure.
- If you sell: the visa depends on continuing to own qualifying property, so a sale that leaves you under the threshold puts the visa at risk.
- If you refinance: changes that reduce your recognised equity or alter the structure may cause questions later.
04Selling the property
This is where owners most often go wrong. If you sell the home and no longer hold AED 2 million or more in qualifying property, you no longer meet the investment condition, and the visa becomes liable to cancellation. In practice the land department and immigration records are linked, so a sale can be held up until the visa side is dealt with.
The safe order is to secure the replacement property first and then complete the sale. Selling first and hoping to sort it out later can leave you with a transfer on hold or a visa to cancel. If you are thinking of selling, tell us before you list.
05Mortgages and refinancing
A mortgaged property counts on its full value, with the bank's letter. If you later refinance, take out a second charge or draw equity, check how that changes your recorded position. A change that undercuts what you can show as your stake may cause trouble when the visa is reviewed.
06A simple plan if values soften
- 1
Do not panic-sell
A fall in price is not a reason to sell, and a sale is the step most likely to harm the visa.
- 2
Keep your documents current
Hold the title deed, mortgage statements and valuation records in one place.
- 3
Look ahead to renewal
If you are years from renewal, you have time to add a property or reduce debt.
- 4
Ask before any change
Selling, refinancing and transfers into a company should all be checked with us first.
Worried about how your own property or plans fit with your visa? Message us on WhatsApp for a free check.
Questions about this topic
Not as far as we know. There is no routine revaluation that cancels visas because of a normal dip.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.