In March 2025, reports in the UAE said that a requirement affecting the property Golden Visa had been removed. Until then, buyers had been asked to have paid a substantial part of the property price, so that an investor with a large mortgage or an unfinished off-plan unit often fell short.
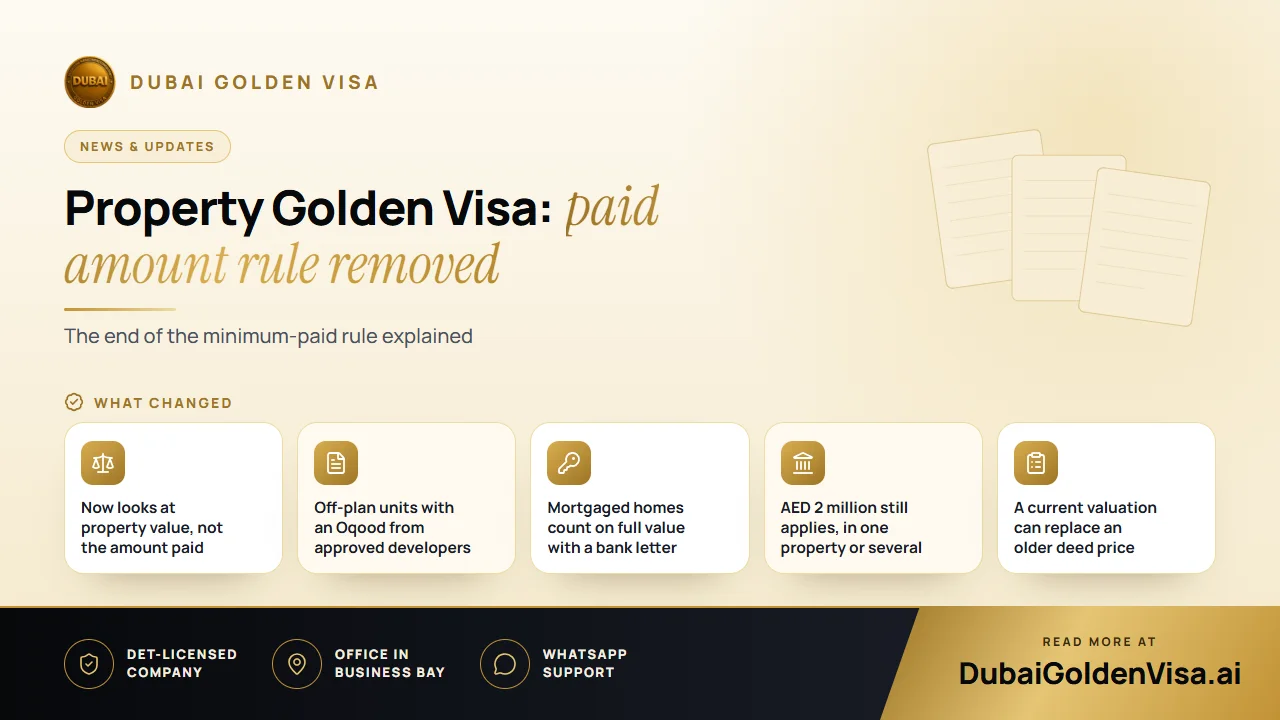
The headline change is that the test is now the property's value rather than the amount you have paid so far. The AED 2 million figure itself did not move. This article explains what that means for different kinds of owners.
01What changed
Under the earlier approach, buyers needed to show a significant payment before the property could support the visa. That tended to rule out recent off-plan buyers on payment plans, and owners with high mortgages. Under the current position, the value of the property is what counts.
- Completed homes count on their registered value.
- Off-plan units from approved developers count whatever you have paid, as long as they are registered with an Oqood.
- Mortgaged homes count on their full value, with a no-objection letter from the bank.
- Several properties can be added together to reach AED 2 million.
02Why it matters for investors
For an investor buying off-plan, the visa no longer has to wait for the construction payments to build up. Someone who has paid a small initial instalment on a qualifying unit may now be able to file much earlier.
For a buyer using a mortgage, it makes the maths simpler. You do not need to pay down the loan to a particular level first. You do need the bank's letter confirming it has no objection to your residency application, so speak to your lender early.
Tip
The rules about value still apply
The threshold is still AED 2 million. If you hold the property jointly, it is generally your own share that needs to reach it. If your deed shows an older price, a current valuation from the Dubai Land Department may help.
03What stays the same
The visa itself has not changed. It lasts ten years, can be renewed and lets you be your own sponsor. You can include your spouse, children and parents, and the usual household staff caps do not apply. You also remain exempt from the six-month absence rule that can cancel a standard residence visa.
The property must still be registered with the land department and be in your name. A sale and purchase agreement without registration is not enough.
04How to apply
- 1
Check your deed or Oqood
Confirm your name, your share and the registered value.
- 2
Get your bank letter or valuation if relevant
A mortgage needs the bank's letter. An older deed may need a current valuation.
- 3
Submit your residency file
If you are abroad, an entry permit brings you in to finish it.
- 4
Medical test and Emirates ID
Both follow initial approval, and your current visa is cancelled only after that.
Property files usually take around five to seven working days once all documents are complete. The main applicant's government costs are about AED 9,459, and each family member's are around AED 2,710 plus AED 1,180 for the Emirates ID, with a medical for adults.
05A note on the market
Commentators expected more interest from off-plan buyers because of the change. We would add a caution: buy a property because it is a good home or investment first. Residency is a welcome extra, not the reason to take on a purchase you would not otherwise make.
If you have an off-plan or mortgaged property and would like to know where you stand, message us on WhatsApp for a free check.
Questions about this topic
It can count if it is from an approved developer, registered with an Oqood and worth AED 2 million or more. We check the registration and developer before filing.
Questions about your own case?
Send us a message and an advisor will tell you which route fits and what you'll need.